A fill on Hyperliquid costs you a share of the notional you traded, not a share of the margin you posted. Almost every misunderstanding about Hyperliquid fees starts there. Read on 2 August 2026, the venue’s own documentation puts the base perpetuals schedule at 0.045% to take liquidity and 0.015% to add it. Volume tiers, staking discounts and referral codes are all multipliers applied to those two numbers. The funding payment that shows up on your position is not a venue charge at all.
The Crypto Trading Starter Kit
A plain-English PDF: what to check before you trade, how orders and risk really work, and the mistakes to skip. Get it free.
TL;DR / Quick insight: As of 2 August 2026, a first-tier perpetuals trader pays 0.045% taking and 0.015% making, and spot pays 0.070% and 0.040%. Fees are charged on notional. A $10,000 position opened and closed with market orders costs $9.00 in total, while the same round trip done with resting limit orders costs $3.00. Volume tiers reward institutional size. Funding is a payment between longs and shorts, not a fee. Rates change, so check the live schedule before you size anything.
Every rate below was read from Hyperliquid’s published documentation on 2 August 2026 and is quoted with that date attached. Fee schedules are revised, tiers get recut and new markets arrive with their own settings. Use this page to understand the structure, and treat the venue’s live schedule as the authority on what you will pay. Nothing here is personal advice. Leverage amplifies losses as well as gains, and a liquidation closes your position whether or not you agree with the price that caused it.
The two numbers that decide your cost
Hyperliquid prices trading the way most order books do. If your order sits in the book and waits, you are a maker, and you are paid for or charged less for supplying the liquidity somebody else needs. If your order crosses the spread and fills against what is already resting there, you are a taker, and you pay more for the immediacy. The gap between those two rates is the single biggest lever an ordinary account has over its trading costs.
Here is the entry-level schedule, the one that applies until your rolling volume crosses the first cutoff.
| Product | Taker fee | Maker fee | Cost on a $10,000 fill (taker) | Cost on a $10,000 fill (maker) |
|---|---|---|---|---|
| Perpetual futures | 0.045% | 0.015% | $4.50 | $1.50 |
| Spot | 0.070% | 0.040% | $7.00 | $4.00 |
Base rates for tier 0, published on the venue’s fees page and read on 2 August 2026. The same numbers appear independently in the API response that the app itself reads. There, the userFees endpoint returns a fee schedule of 0.00045 cross and 0.00015 add for perps. Those decimals are the same 0.045% and 0.015%, expressed as fractions rather than percentages. This is worth knowing, because that endpoint is the honest answer to “what am I actually being charged”.
Two features of this schedule surprise people arriving from a centralised venue. The first is that there is no negotiated arrangement behind it. Hyperliquid’s market-making page is blunt about this: there is no designated market maker programme, no special rebates or fees, and no latency advantages. Whoever is quoting the book you trade against is on a schedule you can read.
The second is that a maker at tier 0 still pays. A true rebate, where the venue pays you to quote, exists on Hyperliquid. It sits behind a separate ladder, and the thresholds are percentages rather than dollar amounts. The published ladder reads: more than 0.5% of 14 day weighted maker volume earns -0.001%, more than 1.5% earns -0.002% and more than 3.0% earns -0.003%. Those rebates are paid out continuously to the trading wallet on each trade. At -0.001%, a $10,000 maker fill pays you ten cents. Ten cents is beside the point. A threshold written as a proportion of the venue’s maker flow describes a professional quoting operation rather than an ordinary account.
The economics of pricing liquidity this way are well studied outside crypto. Market microstructure research on optimal make-take fees for market making regulation models the exchange choosing a fee split that induces market makers to quote tighter. Simulation work on the impact of maker-taker fees on the stock market tests what happens to spreads when the split is adjusted. An on-chain perpetuals venue is running the same idea with the same intention.
Getting the maker rate is a matter of order type, not intent. A limit order that would fill immediately is a taker. The documented route to a guaranteed maker fill is post-only. Hyperliquid exposes it on its order ticket and describes it in the Chase order, a post-only limit order that re-prices to track the best bid or ask. A post-only order that would cross gets cancelled rather than filled at the taker rate. That is exactly the protection you want if the fee difference is the reason you are using it.
How volume tiers change what you actually pay
Your tier is set by rolling 14 day volume, and the fees page is specific about the accounting. Rates are based on your rolling 14 day volume and assessed at the end of each day in UTC. Sub-account volume counts toward the master account, and every sub-account shares the master’s tier. Vault volume is treated separately. There is one tier per user across every asset you touch.
| Tier | 14 day weighted volume | Perp taker | Perp maker | Spot taker | Spot maker | Perp taker cost on $10,000 |
|---|---|---|---|---|---|---|
| 0 | Under $5M | 0.045% | 0.015% | 0.070% | 0.040% | $4.50 |
| 1 | Over $5M | 0.040% | 0.012% | 0.060% | 0.030% | $4.00 |
| 2 | Over $25M | 0.035% | 0.008% | 0.050% | 0.020% | $3.50 |
| 3 | Over $100M | 0.030% | 0.004% | 0.040% | 0.010% | $3.00 |
| 4 | Over $500M | 0.028% | 0.000% | 0.035% | 0.000% | $2.80 |
| 5 | Over $2B | 0.026% | 0.000% | 0.030% | 0.000% | $2.60 |
| 6 | Over $7B | 0.024% | 0.000% | 0.025% | 0.000% | $2.40 |
Base rates as published on 2 August 2026. Now put the ladder in proportion. Reaching tier 1 means $5,000,000 of weighted volume inside a rolling fortnight, which is $357,142.86 every single day for fourteen consecutive days. At ten times leverage on a $10,000 account, a full-size position is $100,000 of notional, and opening then closing it puts $200,000 through the book. You would have to do that nearly twice a day, every day, for a fortnight, and then keep doing it. Reaching the top of the ladder means $7,000,000,000.
The honest reading is that the tier ladder is a wholesale discount aimed at desks and market makers. Its total range is also smaller than the lever you already control. Moving from taker to maker at tier 0 cuts your rate from 0.045% to 0.015%, a reduction of 66.7%. Climbing the entire volume ladder from tier 0 to tier 6 cuts the taker rate from 0.045% to 0.024%, a reduction of 46.7%. A patient limit order beats seven billion dollars of turnover, which is not a sentence you get to write very often.
One further detail matters if you run more than one account. Sub-accounts share the same fee tier as the master account, so splitting your trading across them does not fragment your volume. It does not multiply your discounts either.
Why perpetuals and spot run different schedules
Spot and perpetuals are separate fee schedules on Hyperliquid, and spot is the more expensive of the two at every tier. At tier 0 the spot taker rate of 0.070% is roughly 56% higher than the perp taker rate of 0.045%. The spot maker rate of 0.040% is more than twice the perp maker rate of 0.015%. On a $10,000 fill that is $7.00 against $4.50 taking, and $4.00 against $1.50 making.
The two schedules are separate, but the volume that qualifies you is pooled, and pooled with a thumb on the scale. The published formula is 14d weighted volume = 14d perps volume + 2 x 14d spot volume. In other words, spot volume counts double toward your fee tier even though spot fills cost more. A trader who does both is credited twice over for the spot activity when the venue works out which tier to put them in.
There is a caveat that will bite anyone who assumes one schedule covers the whole venue. Permissionlessly listed markets can carry settings the standard tables do not describe. The fees page states that deployers of such perpetual markets can configure an additional fee share. It adds that activating growth mode on one of them reduces protocol fees, rebates and volume contributions by 90%. Spot pairs quoted between two stable assets, it says, have 80% lower taker fees. Before you trade an unfamiliar market, read what that specific market charges rather than assuming the headline number.
Funding is not a fee, and why the difference matters
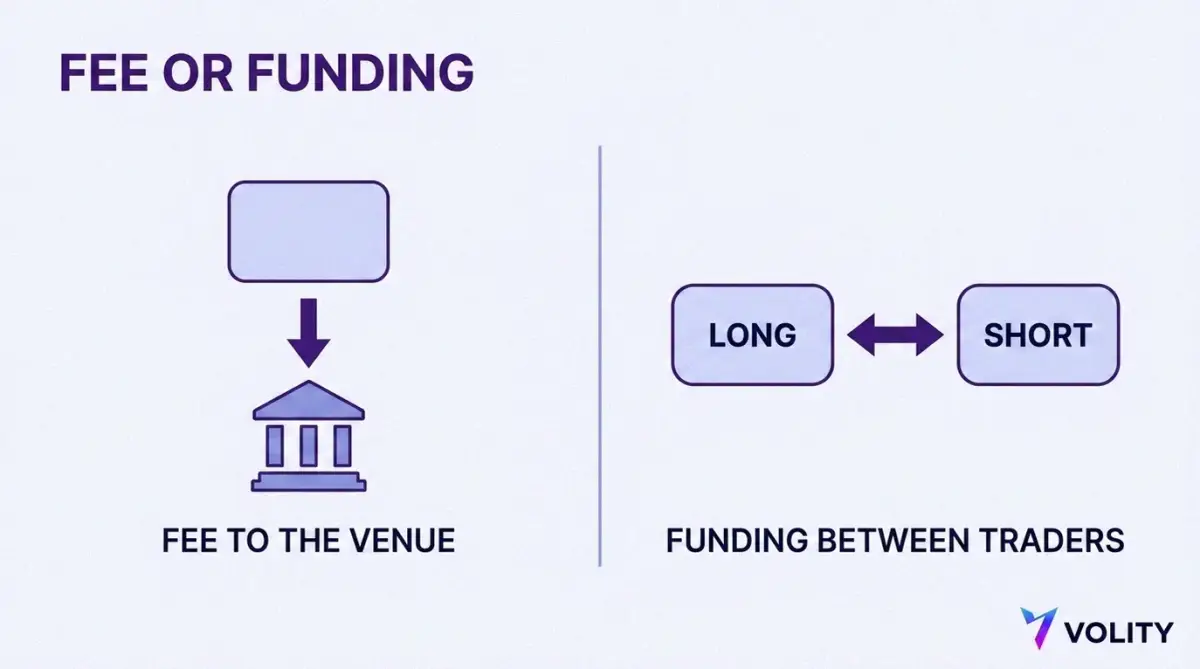
Ask a room of new perpetuals traders what Hyperliquid charges and a good share of them will include funding in the answer. It does not belong there. A fee is money you hand to the venue for the service of matching your order. Funding is money that moves sideways, from one set of traders to another, and the venue keeps none of it. Hyperliquid’s documentation states this without hedging: funding is purely peer-to-peer and no fees are collected on the payments.
The consequences of that distinction are practical rather than academic. A fee is always a cost and always points the same way. Funding points whichever way the market’s positioning is leaning, so it can be a cost on Monday and an income on Tuesday without anything changing about the venue. If the perpetual trades above the underlying spot price, longs pay shorts. If it trades below, shorts pay longs. Hold the unpopular side of a crowded trade and funding pays you for the inconvenience.
Size gives a feel for the two. On Hyperliquid the interest component of the rate is fixed at 0.01% every 8 hours, which is 0.00125% every hour, or 11.6% APR paid to short. Funding is settled hourly at one eighth of the computed 8 hour rate. On a $10,000 position, that baseline is $0.125 an hour, $1.00 every eight hours and $3.00 a day. Three days of holding at that baseline costs the same $9.00 as opening and closing the position with market orders. The premium component moves with the gap between the perpetual and spot prices. In an excited market it dwarfs the baseline in both directions.
Economists treat this quantity as a carry return rather than a charge. The Bank for International Settlements working paper on crypto carry studies exactly this stream. It models the funding rate as the price of leveraged exposure that clears between the two sides of the market. That framing is much closer to reality than “the exchange charges you to hold overnight”. For the full mechanism, including how the premium is sampled and why the rate can invert, see our guide to what a funding rate is in crypto. This page is about what the venue charges, and funding is not that.
Turning a fee rate into a real cost on a real position
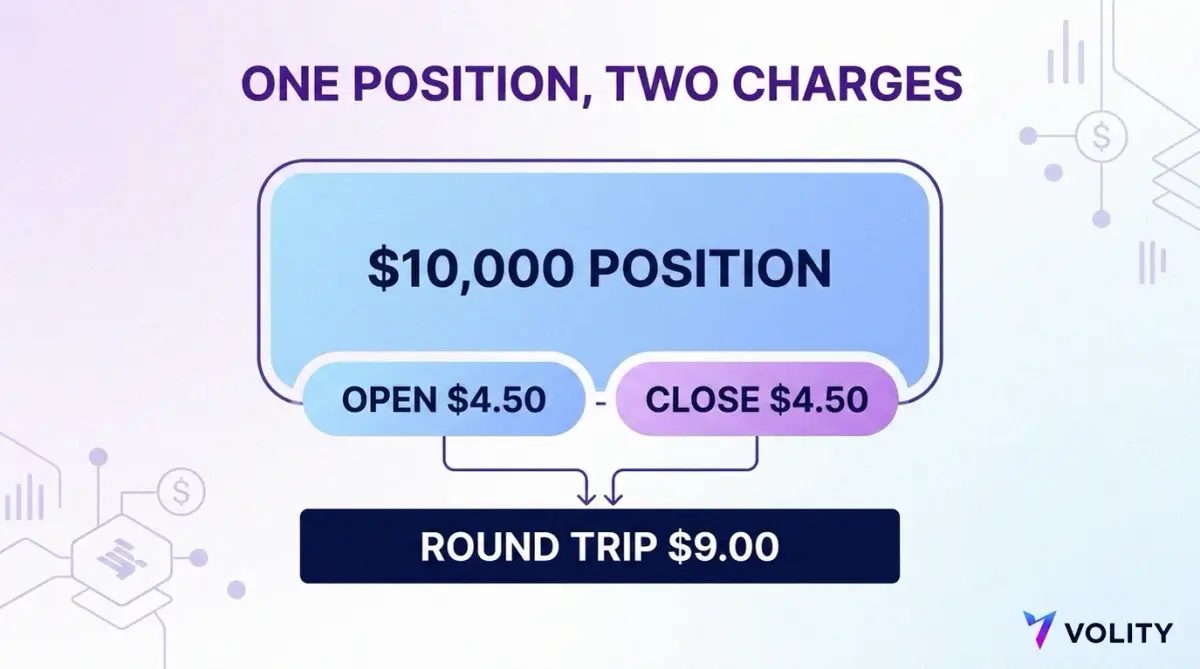
A percentage with three decimal places is easy to wave away. A number in dollars is not, so here is the same schedule expressed as money. Every figure below uses the tier 0 base rates as published on 2 August 2026: 0.045% taker and 0.015% maker on perpetuals.
| Position notional | Market in, market out | Limit in, limit out | Limit in, market out |
|---|---|---|---|
| $1,000 | $0.90 | $0.30 | $0.60 |
| $5,000 | $4.50 | $1.50 | $3.00 |
| $10,000 | $9.00 | $3.00 | $6.00 |
| $50,000 | $45.00 | $15.00 | $30.00 |
| $100,000 | $90.00 | $30.00 | $60.00 |
The arithmetic is one multiplication done twice. A round trip where you take liquidity on both legs costs 0.045% plus 0.045%, which is 0.090% of notional. A round trip made entirely of resting orders costs 0.015% twice, which is 0.030%. Mixing the two, which is what most traders actually do when they enter patiently and exit in a hurry, costs 0.060%.
Now the part that catches leveraged traders. The fee follows the notional, and leverage multiplies notional while leaving your deposit alone. Take a $2,000 margin balance and open the largest position each leverage setting allows.
| Leverage on $2,000 margin | Position notional | Round trip at 0.045% each way | Cost as a share of your margin |
|---|---|---|---|
| 1x | $2,000 | $1.80 | 0.090% |
| 5x | $10,000 | $9.00 | 0.450% |
| 10x | $20,000 | $18.00 | 0.900% |
| 20x | $40,000 | $36.00 | 1.800% |
| 40x | $80,000 | $72.00 | 3.600% |
At forty times leverage, opening and closing once has removed 3.6% of your account before the market has moved a tick. Do that four times in a session and you have spent more than 14% of the balance on execution. This is the mechanism behind most accounts that bleed away without a single dramatic loss, and it is entirely visible in advance.
Express the same thing as a breakeven and it becomes a planning tool. A taker round trip at tier 0 needs the price to move 0.090% in your favour before you are level. A maker round trip needs 0.030%. Neither number depends on the asset or the price, so you can carry them around. Say the move you are trading for is a quarter of a percent. Fees then eat about a third of it at market-order rates, and about an eighth at limit-order rates.
One cost sits alongside the fee and is often larger than it. Crossing the spread is its own charge. If a market is quoted two basis points wide, buying at the ask costs you one basis point against the midpoint. That is $1.00 on a $10,000 fill, on top of the $4.50 fee. On a thinly quoted market the spread can dwarf the schedule entirely. Check the depth of the book before deciding that a low headline fee makes a market cheap.
What an active trader should actually optimise
Order type is the first and largest lever, and the tables above have already made the case. Everything after it is smaller, and two of the mechanisms are commonly described in ways that overstate what they do.
Staking is the first. Hyperliquid publishes a discount ladder keyed to how much HYPE you have staked. The named columns in its fee tables are the resulting rates, not a separate promotion. The discount scales with the size of the staked position. Read the current ladder on the venue’s own fee page, because both the rates and the thresholds are revised.
A discount bought with a token position is not a free discount. Staked HYPE is exposed to the price of HYPE, and getting it back is not instant. Transfers from the staking account to the spot account go through a 7 day unstaking queue. Weigh the saving against the position you have to hold to earn it. At the entry level the saving is measured in cents per $10,000 filled. That is not enough to change how anyone trades.
Referral codes are the second. Hyperliquid’s referrals page states that using a referral code gives a 4% discount on your fees for your first $25M in volume. The discount does not apply to vaults or sub-accounts. It is a discount with an expiry measured in volume rather than time.
How the three stack is where descriptions go wrong, so take the mechanisms one at a time. The volume tier sets your base rate. The staking discount is applied to that base rate. Hyperliquid publishes the result directly in the named columns of its fee tables, not as a separate deduction you apply yourself. The referral discount is then applied by the venue’s published fee formula as a multiplier of one minus the referral discount on the rate the fee endpoint returns. Following that published sequence, a tier 0 trader on the base rate with an active referral code pays 0.045% multiplied by 0.96, which is 0.0432%. On a $10,000 taker fill, that comes to $4.32. Your account’s live rate is the one the app and the fee endpoint report. Trust that number over any arithmetic done on a blog.
Two costs never appear on the fee schedule at all and can outweigh it. Withdrawing from Hyperliquid carries a withdrawal gas fee of 1 USDC, paid on Hyperliquid to cover the validators’ Arbitrum gas costs. This means you do not need to hold any Arbitrum ETH yourself. The single dollar is 0.020% of a $5,000 withdrawal and 0.500% of a $200 one. It argues for moving money in sensible sizes rather than in dribs.
The larger one is liquidation. Hyperliquid first tries to close a failing position through the order book, and if account equity falls below two thirds of the maintenance margin a backstop liquidation happens instead. In that case, the maintenance margin is not returned to the user, and maintenance margin runs between 1.25% and 16.7% of notional depending on the asset’s maximum leverage. Losing 1.25% of notional in one event is the equivalent of about fourteen taker round trips. A stop loss placed in advance is the cheapest fee-management decision on this list, and our guide to margin health and liquidation price covers how to see that number coming.
How to work out your cost before you open
Run this before the order, not after the fill. It takes under a minute and it is the same sequence every time.
- Work out the notional. Multiply the size you intend to trade by the price, and ignore your margin entirely. Notional is what the fee is charged on.
- Read your live rate in the app rather than assuming tier 0. The fee endpoint the interface reads returns your current maker and taker rates including any tier and staking adjustment.
- Decide the entry order type and the exit order type honestly. If you know you will close in a hurry, price the exit at the taker rate.
- Multiply notional by the entry rate, then by the exit rate, and add the two. That is your round trip in dollars.
- Add the spread you expect to cross on each leg, valued in the same way. On a wide market this can exceed the fee.
- Turn the total into a breakeven move as a percentage of the entry price and compare it with the move you are actually trading for. If fees plus spread are a large fraction of your target, the trade is too small or the market is too illiquid.
- If you plan to hold overnight, look up the current funding rate separately and treat it as a cash flow that may run either way, not as a charge.
The rest of this cluster fills in the surrounding ground. Our explainer on what Hyperliquid is covers the on-chain order book the fee schedule pays for. A separate guide on how to fund a Hyperliquid account walks through getting margin in place. Our comparison of perp DEX versus centralised exchange looks at the two models on custody and transparency. For fees closer to home, our page on crypto trading fees sets out what trading costs on Volity itself. The wider crypto guides cover the rest.
Where Volity fits
The Markets screen in your Volity dashboard lets you connect a Hyperliquid account and fund it from your Volity USD wallet. From the same place you manage the rest of your money, you can watch available balance, account value, margin used, open positions and unrealised P&L. The panel labels those figures as held at Hyperliquid and stamps them with a refresh time. That way you always know which side of the connection you are looking at.
The fees on this page are Hyperliquid’s own and are charged by Hyperliquid. Your balances and positions are held on the external platform, and trading, availability and withdrawals are subject to that platform’s terms. Volity does not place or manage orders on your behalf. What our side gives you is one funding route and one view of the balance, which leaves the arithmetic above as the only work you have to do yourself.
What is the difference between a maker and a taker fee?
A maker order rests in the order book and waits for somebody else to trade against it, which adds liquidity to the venue. A taker order crosses the spread and fills against orders already sitting there, which removes liquidity. Hyperliquid charged 0.015% for perpetuals makers and 0.045% for perpetuals takers at the entry tier as of 2 August 2026, so the taker rate is three times the maker rate. Post-only orders are the documented way to guarantee you land on the maker side, because a post-only order that would cross gets cancelled instead of filled.
How do I qualify for a lower fee tier?
Tiers are set by rolling 14 day volume, assessed at the end of each day in UTC, with the first cutoff at $5,000,000 of weighted volume. That works out at $357,142.86 a day for fourteen days straight. Spot volume counts double toward the calculation and sub-account volume counts toward the master account. For most traders the tier ladder is out of reach, and switching from market orders to resting limit orders delivers a bigger cut than the whole ladder does.
Is funding a fee?
No. Funding is a payment between traders holding opposite sides of a perpetual contract, and Hyperliquid’s documentation states that it is purely peer-to-peer with no fees collected on the payments. It can be a cost or an income depending on which way the market is leaning, whereas a trading fee is always a cost and always goes to the venue. Funding on Hyperliquid settles every hour, and the fixed interest component is 0.01% every 8 hours as of 2 August 2026.
How much does one trade cost on Hyperliquid?
Multiply the notional by the rate. At the entry tier as of 2 August 2026, a $10,000 perpetuals position costs $4.50 to open with a market order and $4.50 to close with one. That makes $9.00 for the round trip. The same round trip done with resting limit orders costs $1.50 each way, or $3.00. Because the fee is charged on notional rather than margin, five times leverage on $2,000 of margin turns that $9.00 into 0.45% of your account.
Are spot and perp fees the same?
No, spot is dearer at every tier. At the entry tier as of 2 August 2026, spot charged 0.070% taker and 0.040% maker, against 0.045% and 0.015% on perpetuals. On a $10,000 taker fill, that is $7.00 versus $4.50. The volume that qualifies you is pooled across both, and spot volume counts double toward your tier. Rates are revised from time to time, so check the venue’s live schedule before you trade on any of these numbers.