Risk assets are investments whose prices rise and fall with market confidence: shares, high-yield corporate bonds, commodities and crypto. Government bills and cash sit at the other end. The label describes how an asset behaves in a given period, and both gold and government bonds have changed sides in recent stress. This guide shows what moves risk assets together, what the long record says, and how to size a position before you test it on a free demo.
TL;DR: A risk asset pays more over time because it can fall hard. US shares beat Treasury bills by 8.44 percentage points a year on average from 1928 to 2025, but lost 36.55% in 2008. Safe assets can fail too: in 2022 shares and 10-year Treasuries fell together. Size each trade from the loss you accept at your stop, then practise on a demo.
The question is live. In its July 2026 Financial Stability Report, the Bank of England’s Financial Policy Committee wrote: “Meanwhile, risky asset prices have reached high levels.” It added that rising equity prices were driven “in part, by a narrow set of AI-related companies, increasing market concentration”. High prices and narrow leadership are the conditions in which risk assets can fall together.
What counts as a risk asset
Central banks use the term for assets whose prices move with investors’ appetite for risk. The Bank for International Settlements (BIS), the central banks’ own bank, wrote in its December 2025 Quarterly Review: “Strong risk sentiment and expectations of policy easing supported risk assets, but growing wariness and higher volatility increasingly challenged the risk-on mood.” Mood, policy and volatility drive the group as a whole.
The usual list looks like this:
- Shares and stock indices, with small companies at the riskier end.
- High-yield corporate bonds, which pay more because the issuer may default.
- Commodities such as oil and industrial metals.
- Crypto assets such as bitcoin.
- Property, in some definitions.
Think of a spectrum rather than two boxes. Aswath Damodaran of NYU Stern publishes US annual returns since 1928, in a table updated in January 2026 that runs to 2025. Recomputed from that table, yearly returns on 3-month Treasury bills had a standard deviation of 3.0%. Standard deviation measures how widely yearly returns spread around their average. For the S&P 500 including dividends it was 19.4%, and for US small caps 37.9%.
Banks also use “risk assets” in a narrower sense, for the loans and holdings they weigh when they set capital. This guide uses the market sense.
What investors are paid for holding risk assets
The reward for that spread of outcomes is called the risk premium: the extra return over a nearly riskless asset. On the same table, the S&P 500 including dividends returned 8.44 percentage points a year more than 3-month Treasury bills on simple (arithmetic) averages from 1928 to 2025. On compounded (geometric) averages, the gap was 6.65 points: 10.02% a year against 3.37%. Estimates of the premium vary with the years, the benchmark and the averaging method, so treat any single number as one estimate.
The price of that premium is the bad years. The S&P 500 lost 43.84% in 1931 and 36.55% in 2008, and it ended the year lower in 26 of the 98 years in the table. An investor who needed the money in one of those years took the loss. A premium is an average over decades and promises nothing for the next twelve months.
To compare assets on reward per unit of risk, analysts use ratios such as the Sharpe ratio, which divides the return above a risk-free rate by volatility.
How risk-on and risk-off moods show up in prices
In a risk-on period, investors buy riskier assets, and shares, credit and crypto tend to rise together. In a risk-off period they sell them and move into cash, short-dated government bills or currencies seen as safe. The BIS described one sign in its March 2026 Quarterly Review: “the Swiss franc appreciated notably, a hallmark of global risk-off episodes”.
Traders watch a few gauges to read the mood:
- Equity indices, as the broadest price of risk.
- The VIX, the volatility index traders watch, listed by Cboe.
- Credit spreads, the extra yield on corporate bonds over government bonds.
- Interest-rate expectations and real yields, meaning yields after inflation.
You can check the rate side yourself on official pages: the Bank of England yield curves, the US Treasury’s daily real yield curve and the ECB euro area yield curves. None of these gauges forecasts the next move. They tell you which mood the market is in now, so you can judge whether your position is swimming with it or against it.
When safe assets fall with risky ones
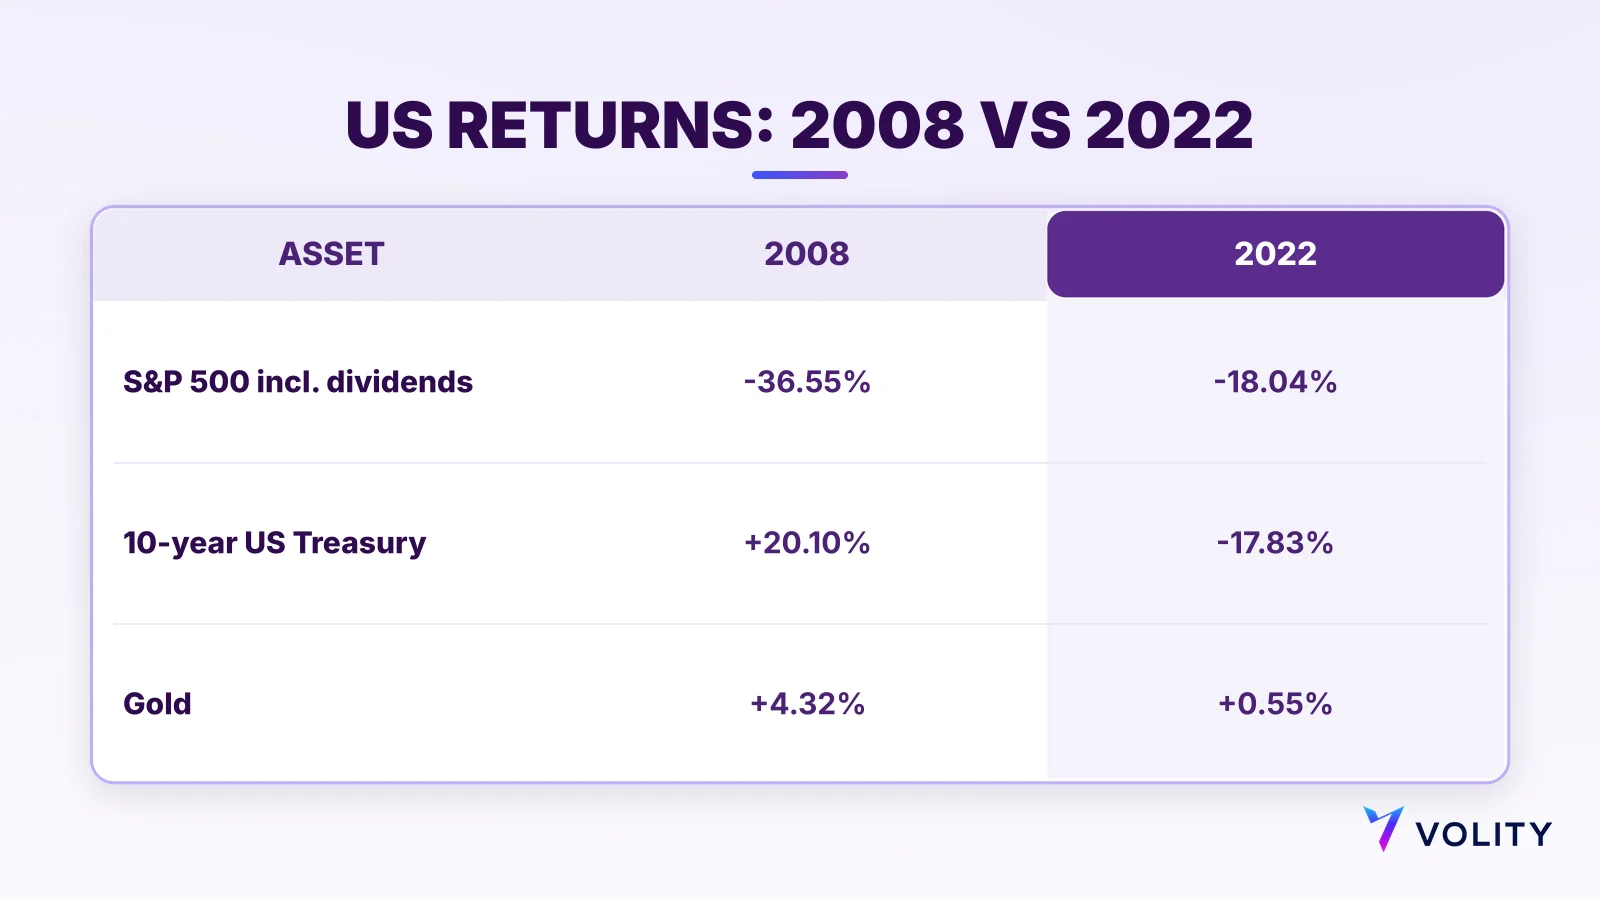
The classic risk-off trade assumes that government bonds rise when shares fall. Often they do. Sometimes they do not, and a portfolio built on that assumption loses on both sides.
| Calendar year (US returns) | 2008 | 2022 |
|---|---|---|
| S&P 500 incl. dividends | -36.55% | -18.04% |
| 10-year US Treasury bond | +20.10% | -17.83% |
| Gold | +4.32% | +0.55% |
The figures come from the Damodaran table. In 2008 the bond leg did its job: shares fell 36.55% and 10-year Treasuries gained 20.10%. In 2022 shares fell 18.04% and 10-year Treasuries lost 17.83%, their worst year in the table, as interest rates rose fast. Baa-rated corporate bonds lost 15.23% the same year.
Stress can break the pattern within days. In a 2022 speech on the March 2020 “dash for cash”, Bank of England Deputy Governor Jon Cunliffe described 9 to 18 March 2020. He cited “10 year US treasury yields rising by 65 bps in this period and 10 year gilt yields moving 64 bps higher.” A rising yield means a falling bond price. He added: “Bid-offer spreads on US treasuries widened by a factor of 10. The gold price fell by 12%.” Investors sold whatever they could to raise cash.
So “safe” is also behaviour in a period. Our upcoming guide to safe haven assets looks at that side in depth. For the stock and gold record across these episodes, see our analysis of the correlation between gold and stocks.
Bitcoin and gold sit on the borderline
Bitcoin was once pitched as a hedge. In a January 2022 IMF blog, Tobias Adrian, Tara Iyer and Mahvash Qureshi wrote that “returns on Bitcoin and the S&P 500 had a correlation coefficient of 0.01 in 2017-19.” They continued: “That correlation jumped to 0.36 for 2020-21”. Correlation runs from -1 to +1, and a higher figure means two prices tend to move the same way. On that 2017-21 sample, bitcoin behaved more like a stock.
Gold is harder to place. Over 1928-2025, the annual returns of gold and the S&P 500 had a correlation of -0.06 in the Damodaran table, close to zero. Annual data hides short episodes, though. The December 2025 BIS review noted: “Throughout the recent market rally, US equities and gold surged in lockstep.” By March 2026, the BIS wrote that “precious metals came under renewed pressure, trading more like risk assets than safe havens”.
The price backdrop is high. The World Gold Council’s Gold Demand Trends Q3 2026 reports that “The LBMA (PM) gold price averaged US$4,262/oz in Q3”, 23% higher than a year earlier. The LBMA Gold Price is the daily London benchmark. Our guide to what XAU means explains how gold is quoted for trading.
Size the position from the loss you accept
Since any risk asset can fall hard, start from the loss you can accept on one trade, not from the profit you hope for. A hypothetical example with round numbers shows the method.

Say your account holds $10,000 and you accept a loss of 1% on any single trade, which is $100. You want to buy an index CFD at 6,000, with a stop-loss at 5,950. A stop-loss is an order that closes the trade at a price you choose if the market moves against you. Here the stop sits 50 points below your entry. Your size is $100 divided by 50 points, or $2 per point.
That position controls $12,000 of the index, more than your whole account. With leverage of 1:500, the margin, the deposit the trade ties up, would be $24. Leverage changes how much cash the trade ties up. The loss at your stop stays near $100, plus the spread. In a fast market a stop can fill at a worse price than you set, a gap known as slippage, so leave room for it.
Now picture the same position with no stop in a year like 2008, when US shares fell 36.55%. A fall that size on $12,000 costs $4,386, almost 44% of the account. Losses are also harder to recover than they look: a 20% fall needs a 25% gain to get back to the start, and a 50% fall needs 100%. The drawdown calculator runs these sums for any figure. You can also offset part of an exposure with an opposite position, known as hedging.
Testing a risk-asset trade on Volity
On Volity you can trade most risk assets from one account: real shares, fractional shares, crypto and CFDs, with more than 350 CFD instruments. A CFD, or contract for difference, pays the change in an asset’s price without you owning the asset. You can go long if you expect a rise or short if you expect a fall, so a risk-off view can be traded from the same account as a risk-on one.
Leverage goes up to 1:500 on forex, metals, index CFDs and commodities, up to 1:50 on crypto CFDs and up to 1:20 on stock CFDs. Leverage magnifies losses as much as gains, which is why the sizing step above comes first. Crypto and a growing range of other markets, including gold, silver, US500, US100 and WTI, trade 24/7; forex trades 24/5. Spreads are dynamic and start from 0.6 pip, and the Markets account is commission-free. The full cost schedule is on the Volity charges and fees page.
The free demo is available on every account tier, and runs on live prices. Use it to run the sizing check before any real money is involved:
- Open the free demo and pick one risk asset, such as US500, gold or bitcoin.
- Write down your test balance and the share of it you accept to lose on one trade.
- Mark the price where your idea is wrong, and set the stop-loss there.
- Divide your accepted loss by the stop distance to get the size.
- Check the live spread on the order ticket and the margin the trade ties up.
- Place the trade, then compare the result at the stop with your own sums.
A Volity Markets account starts from $1, with funding from 10 EUR. Volity operates under CySEC licence 186/12 via UBK Markets, with entities in Saint Lucia, Cyprus and Hong Kong. The gold trading platform page covers spot gold on Volity.
The label “risk asset” will not tell you what happens next. What you control is the size. If you can state your loss at the stop before you click, the position fits your account.
Fact check: long-run US returns, premiums and the 2008 and 2022 rows were recomputed from Aswath Damodaran’s historical returns table (NYU Stern, updated January 2026, data 1928-2025). Market commentary from the BIS Quarterly Reviews of December 2025 and March 2026, the Bank of England Financial Stability Report of July 2026 and Jon Cunliffe’s 2022 speech. Bitcoin correlation from the IMF (January 2022). Gold price from the World Gold Council (Q3 2026). Volity details from volity.io. Checked 11 November 2026.
Frequently asked questions
What is a risk asset?
It is an asset whose price moves with market confidence and can fall sharply, such as shares, high-yield bonds, commodities and crypto. Investors hold them for a higher expected return than government bills or cash.
Is gold a risk asset?
It depends on the period. Gold rose in 2008 and 2022, years when the S&P 500 fell. Yet it fell 12% between 9 and 18 March 2020, and in March 2026 the BIS said precious metals traded “more like risk assets than safe havens”.
Is bitcoin a risk asset?
On the evidence so far, yes. The IMF found that its correlation with the S&P 500 rose from 0.01 in 2017-19 to 0.36 in 2020-21, so it tended to move with shares rather than against them.
Are government bonds risk assets?
They are usually treated as the safer side. In 2022, though, 10-year US Treasuries lost 17.83% while US shares fell 18.04%. When rates rise fast, bond prices fall, so their safety depends on the cause of the stress.
What does risk-off mean?
Risk-off describes a period when investors sell shares, credit and crypto and move into cash, short-dated government bills or currencies such as the Swiss franc. Risk-on is the opposite mood, when riskier assets rise together.
How much of a portfolio should be in risk assets?
There is no single right share. It depends on your goals, your time horizon and how large a fall you can absorb. A 50% fall needs a 100% gain to recover, so test the size on a demo first.